
Bank makes debt consolidation more affordable as households combine retail accounts, personal loans, medical bills and credit cards to improve monthly cash flow.
As South African households continue to grapple with rising living costs and tighter monthly budgets, FNB has removed initiation fees from its qualifying Credit Switch debt consolidation solution, making it more affordable for customers to simplify and manage their credit commitments.
The move is aimed at reducing one of the upfront costs associated with debt consolidation, enabling qualifying customers to combine multiple debts into a single repayment structure. According to FNB, this can help customers better manage their finances while potentially improving their monthly cash flow.
FNB Retail Loans CEO, MJ Davis, says many consumers are seeking greater control over their credit but are often discouraged by the costs involved in switching providers and consolidating debt.
“Customers want to feel more in control of their credit, but the cost of switching providers and consolidating debt can sometimes create hesitation,” says Davis. “By permanently removing an upfront cost barrier like the initiation fee, we are making it easier for qualifying customers to consider consolidation as a practical way to simplify their repayments and potentially improve their monthly cash flow.”
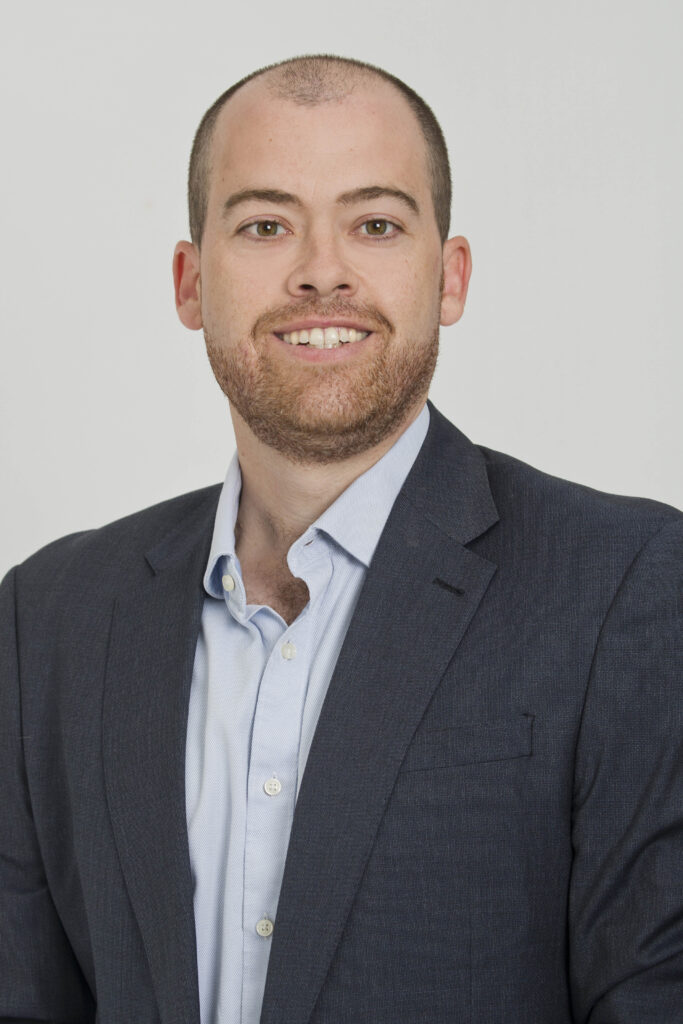
FNB Retail Loans CEO, MJ Davis. Photo supplied
The bank has observed a growing trend of customers consolidating a wide range of financial commitments, including retail accounts, personal loans, instalment accounts, medical bills, revolving credit facilities and credit cards. With these obligations often spread across multiple financial institutions, varying repayment dates, interest rates and fees can make household budgeting increasingly difficult.
“Debt pressure doesn’t always come from one large loan,” Davis explains. “For many customers, it’s the combined effect of several smaller commitments that gradually place strain on their monthly budget. Consolidation can help bring those repayments into one place, making it easier to track, manage and plan around.”
FNB Integrated Advice Product Head, Ester Ochse, says the benefits of debt consolidation extend beyond reducing the number of monthly repayments. She notes that simplifying debt provides households with greater financial visibility and a clearer understanding of their overall obligations.
“When customers carry multiple credit commitments across different providers, it can often become difficult for them to fully grasp how much is going out each month and where the pressure points lie,” says Ochse. “By consolidating and structuring their debt more clearly, we help households build a more accurate view of their obligations, which is a critical first step in managing debt responsibly.”
She adds that digital tools such as My Advisor further support customers by providing a broader picture of their financial position and helping them evaluate available options based on their individual circumstances.
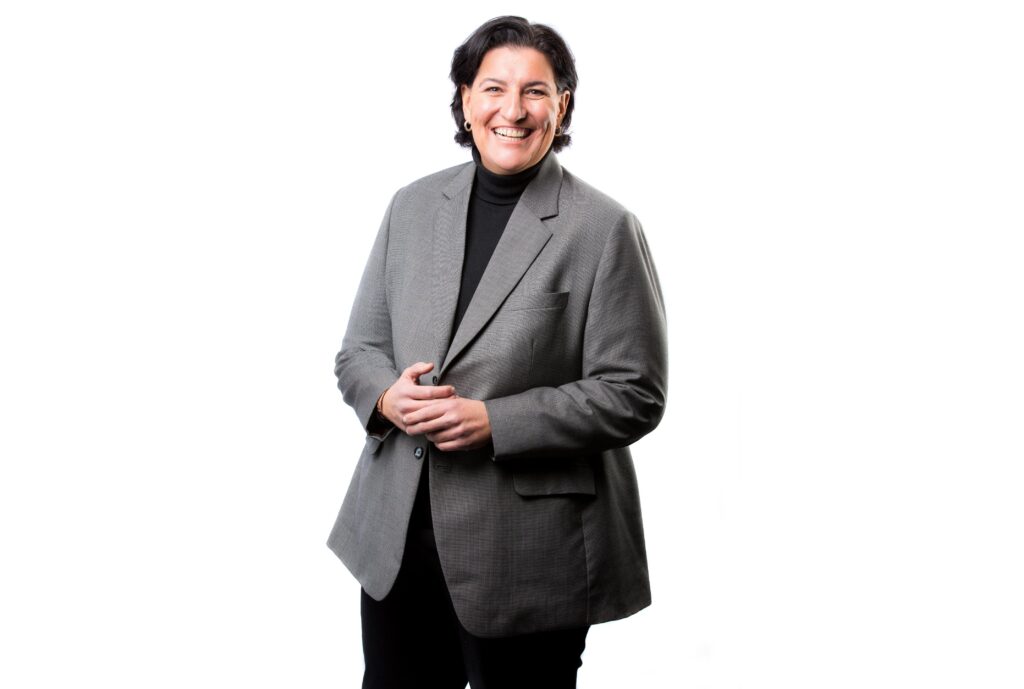
FNB Integrated Advice Product Head, Ester Ochse. Photo supplied
According to Ochse, improved visibility enables households to budget with greater confidence, better align spending with income, and make more informed financial decisions that contribute to long-term financial stability.
The bank says its debt consolidation offering is already delivering tangible benefits. Between July 2025 and April 2026, FNB helped customers unlock R60 million in monthly cash-flow benefits through debt consolidation, highlighting the impact that simplified credit management can have on easing financial pressure.
With the removal of initiation fees, qualifying customers could potentially free up as much as R1,000 in monthly cash flow, depending on their credit profile, affordability assessment and loan terms.
The Credit Switch solution allows customers to combine multiple debts held with different providers into a single repayment with one interest rate, offering a simpler repayment structure that can be managed through the FNB Banking App or with assistance through the bank’s service channels.
While the bank believes simplifying debt is an important step, Ochse says many consumers first need confidence to take action, particularly when reassessing affordability and identifying which financial commitments place the greatest strain on their budgets.
FNB’s customer insights show that many consumers begin reviewing their finances during January and February before taking action from March onwards, once they have a clearer understanding of their affordability and available options.
“Credit management should feel simpler, not more complicated,” Davis concludes. “Our intent and commitment are to make that decision easier whenever customers are ready to act and take control of their credit over the long term.”